READ THE FULL CCLD RESEARCH REPORT
While CareCloud’s (NASDAQ: CCLD) Q3 came in largely as expected, it is stunning how margins have improved as merger integration costs ended, AI reduced internal costs, and the company revamped its finances by eliminating the Series B Preferred and replacing it with tax-deductible, lower-cost debt. The company grew revenues 9%, operating income 105%, net income to common shareholders 147%, and GAAP EPS 146%, and non-GAAP EPS 32%. We expect Q4 to be seasonally weaker and without one-time benefits that occurred in Q3.
The company has shown improvements using AI internally, where it can handle a great portion of processes that had been done manually and with fewer mistakes. This enables more work to be done with fewer people, and the savings show up in gross margin. It has also had success selling its new AI products.
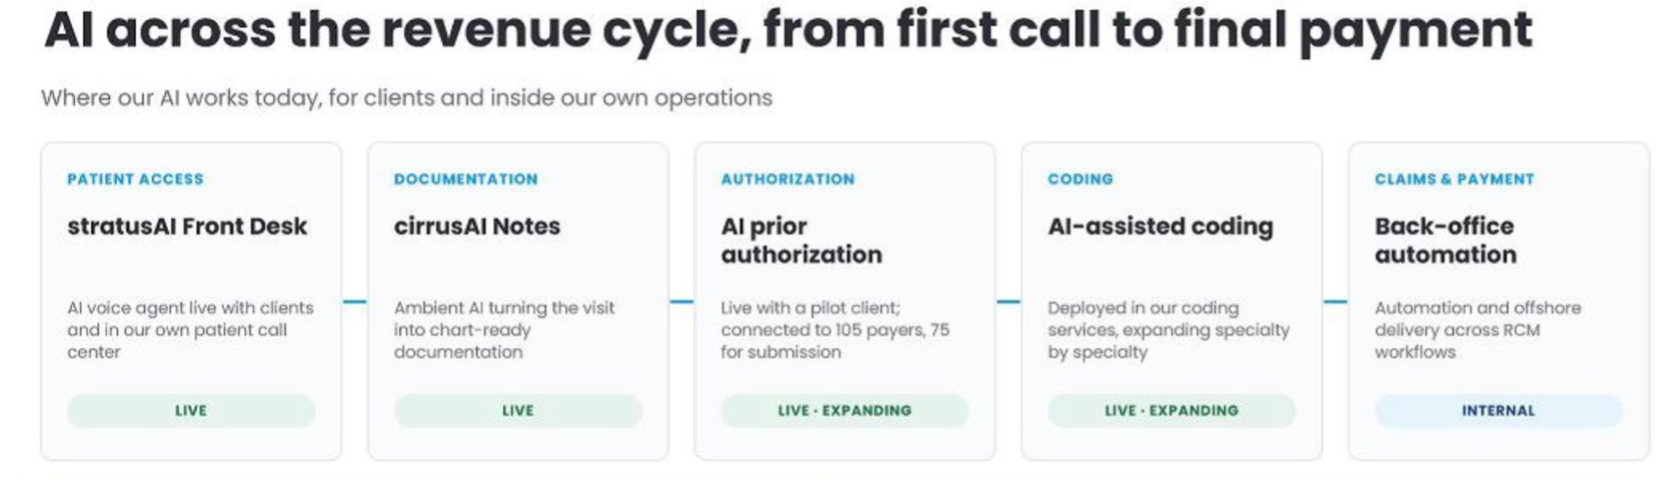
StratusAI Front Desk is CareCloud’s completely customizable 24/7 front desk agent that instantly turns missed calls into captured revenue while the customer can focus on more complex issues and delivering exceptional in-office care.
CirrusAI Notes is CareCloud’s AI-powered solution for real-time clinical documentation that turns complex patient data into actionable insights.
Coming later this year are three new products, as shown below. AI prior authorization is in beta testing, and the other two are being used internally. Also planned is a SaaS product coming from Empower for compliance.
Source: CareCloud
Q3 Earnings Results
CareCloud reported Q3 2026 revenues of $33.7 million versus $31.1 million a year ago, up 8.6%. The increase of $2.7 million was entirely due to the acquisitions of Medsphere (August 22, 2025), which contributed $6.3 million this quarter versus $3.4 million in last year’s quarter, and Empower, which was bought on May 15th and contributed $787,000 in the September quarter. The medSR revenue, which is project-based, decreased by approximately $1.5 million.
Total expenses were down $707,000 over last year. Direct operating costs increased by $485,000: outsourcing and processing costs increased by $895,000, salary costs decreased by $296,000, and billable expenses decreased by $132,000.
R&D was down $582,000 to $1.1 million as the company capitalized a greater portion of software development costs, partially offset by higher legal, consulting, and computer costs.
G&A was basically flat, with an increase of only $64,000. Salary costs decreased by $210,000. The cost for the newly purchased aircraft was $115,000. Depreciation and amortization increased by $857,000.
Operating income was $6.8 million versus $3.2 million last year.
Interest expense was $1.8 million, an increase of $1.7 million. The increase was due to the amortization of the warrant of $934,000 awarded to the Executive Chairman as compensation for the pledge of collateral, and the borrowings under the term loan and the line of credit during 2026. Interest expense and fees on the term loan were $693,000. Interest expense and fees on the line of credit were $125,000.
In Q3, taxes were $127,000 versus $43,000 last year. Net income was $4.7 million compared to $3.1 million last year, representing the company’s tenth consecutive positive net income quarter.
Net income attributable to common shareholders was $4.2 million versus $1.7 million last year. With the preferred redemption, the preferred stock dividend was reduced to $538,000 compared to $1.4 million in Q3 2025. EPS was $0.10 versus $0.04. Non-GAAP adjusted EPS totaled $0.14, flat versus $0.10 last year.
Balance Sheet
The company ended the September quarter with $4.6 million in net cash, negative working capital of $4.2 million, and a current ratio of 0.9x. It now has $37.3 million in debt due to the redemption of the Series B preferred stock. For the quarter, CareCloud generated $5.5 million in cash flow, not including changes in working capital, and had free cash flow of $4.2 million. It is working to pay down its debt rapidly and, as of November 4th, had reduced it to $34.2 million.
SUBSCRIBE TO ZACKS SMALL CAP RESEARCH to receive our articles and reports emailed directly to you. Please visit our website for additional information on Zacks SCR.
DISCLOSURE: Zacks SCR has received compensation from the issuer directly, from an investment manager, or from an investor relations consulting firm, engaged by the issuer, for providing research coverage for a period of no less than one year. Research articles, as seen here, are part of the service Zacks SCR provides and Zacks SCR receives payments totaling a maximum fee of up to $50,000 annually for these services provided to or regarding the issuer. Full Disclaimer HERE.